BEEF PACKERS RESEARCH SERIES | RESEARCH PAPER
Captive in Practice
Why “independent” is the wrong word for most U.S. cattle feedlots: contracts, distance to the nearest packing plant, and what the public record can and cannot show.
Prepared for publication by Farm Animal Transparency | September 2026
A feedlot is independent only if it can walk away from a packer. For most fed cattle, a contract or the map has already made that decision.
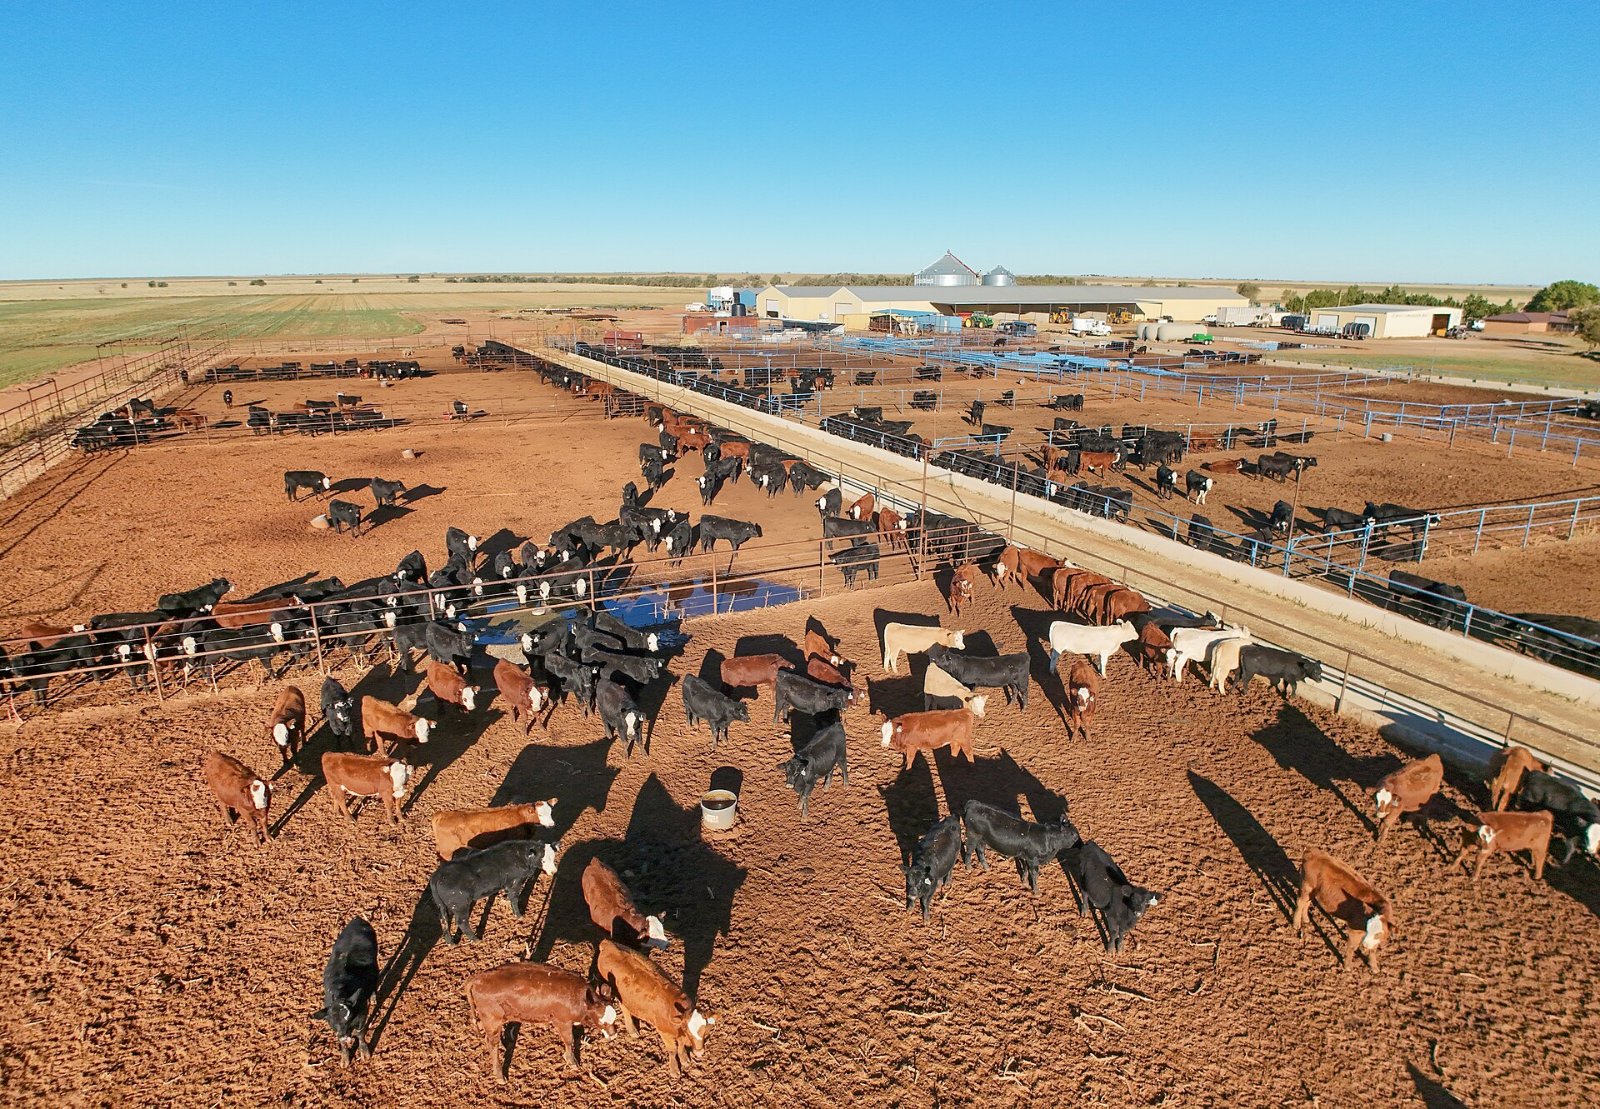
| At a glance |
| Contracts dominate. USDA data show negotiated cash fell from 52.1% of fed-cattle purchases in 2005 to 19.5% in 2021. In the week ending September 20, 2026, about 70% of five-area purchases were formula-priced and about 17% negotiated cash. |
| Distance narrows choice. Of 312 Kansas and Nebraska feedlots in FAT’s dataset (4.63 million head of one-time capacity), 24% have exactly one major fed-cattle plant within 50 miles and 48% have none; 28% have two or more. |
| Packers do not need to own feedlots. JBS sold Five Rivers Cattle Feeding in 2018; the sale included a long-term agreement for Five Rivers to supply cattle to JBS. Five Rivers now runs 13 feedyards with more than 865,000 head of capacity. |
| The law that makes this visible is on a short leash. Livestock Mandatory Reporting authority has run on short extensions since 2020; the current one expires September 30, 2026. |
Abstract
Maps of the U.S. cattle-feeding industry, including FAT’s, label most feedlots “independent” because no packer owns them. This paper argues that ownership is the least important of three ties between a feedlot and a packer. The other two are contracts, visible in aggregate through USDA’s Livestock Mandatory Reporting (LMR) data, and geography, measurable as the number of major fed-cattle plants within hauling distance. We update the LMR record, recompute FAT’s plant-distance analysis for Kansas and Nebraska against a verified September 2026 plant list, summarize the federal policy record and the economics literature, and propose a definition of “captive in practice.”
1. Three ties between a feedlot and a packer
- Ownership: the packer owns the feedyard. On the public record this is now rare among the four largest packers. Investigate Midwest reported in 2026 that the Big Four “do not currently own feedlots outright” and rely instead on supply agreements.
- Contract: the cattle are committed before slaughter through a formula, forward contract or marketing agreement. USDA reports the aggregate share weekly but does not name feedlots.
- Geography: the feedlot has one realistic buyer because only one plant is within economic hauling distance. Oklahoma State University Extension estimates that cattle lose “approximately 1% of their body weight per hour for the first three to four hours” in transit.
The Five Rivers example. In January 2018 JBS sold Five Rivers Cattle Feeding, then 11 feedyards with more than 900,000 head of capacity, to affiliates of Pinnacle Asset Management for about $200 million. The sale included “a long-term agreement to supply cattle to JBS USA beef processing plants.” Five Rivers today lists 13 feedyards in Colorado, Kansas, Oklahoma, Texas, Arizona and Idaho with more than 865,000 head of capacity. Ownership ended; the sale created a long-term supply relationship. A public map that shows only ownership would call these yards independent.
2. Contracts: what Livestock Mandatory Reporting shows
The Livestock Mandatory Reporting Act of 1999 requires packers that slaughtered an average of 125,000 or more cattle a year over the prior five years to report each purchase by type: negotiated (cash), negotiated grid, formula marketing arrangement, forward contract, and packer-owned. Congress reauthorized the law in 2006, 2010 and 2015 (through September 30, 2020). Since then, USDA notes, authority “has been maintained through a series of Continuing Resolutions,” most recently Public Law 119-37, which runs to September 30, 2026.
| Year | Cash | Formula | Forward contract | Negotiated grid |
|---|---|---|---|---|
| 2005 | 52.1% | 33.2% | 4.8% | 9.9% |
| 2010 | 37.4% | 43.1% | 11.9% | 7.6% |
| 2015 | 21.3% | 57.0% | 17.5% | 4.2% |
| 2020 | 23.4% | 62.7% | 8.9% | 5.0% |
| 2021 | 19.5% | 61.0% | 10.9% | 8.6% |
Source: USDA AMS, “Annual LMR Live Cattle Purchase Type Breakdown by Region,” 2005–2021 (national). The table labels the first column “Cash.” A single recent week for comparison: for cattle priced in the week ending September 20, 2026, USDA’s five-area reports show 206,807 head bought on formula, 49,154 through negotiated cash, 28,003 on negotiated grids and 9,298 on forward contracts, which works out to about 70%, 17%, 10% and 3%.
Regions differ sharply. The same USDA table shows cash shares in 2021 of 47.5% in Iowa–Minnesota, 31.1% in Nebraska, 12.5% in Kansas and 7.4% in Texas–Oklahoma–New Mexico. In 2005 the corresponding figures were 73.9%, 64.6%, 50.6% and 47.2%. The Southern Plains, where the largest feedlots and plants are, moved furthest from cash trade.
3. Geography: FAT’s plant-distance analysis, recomputed
Method. For each feedlot in FAT’s supply-map dataset drawn from the Kansas Annual Feedlot Report 2026 and the Nebraska Cattle Feeders Directory, we counted major fed-cattle slaughter plants within 50 miles (straight-line distance from the geocoded location, city centroid where a street address could not be matched). We removed 36 duplicate rows and excluded dairies. The plant list, verified against company sources in September 2026, is: Tyson (Dakota City NE, Holcomb KS, Amarillo TX); Cargill (Dodge City KS, Fort Morgan CO, Schuyler NE, Friona TX); JBS (Cactus TX, Grand Island NE, Greeley CO, Omaha NE, Tolleson AZ, Hyrum UT); National Beef (Dodge City KS, Liberal KS, Tama IA); and four independents (Creekstone Farms, Arkansas City KS; Greater Omaha Packing, Omaha NE; Sustainable Beef, North Platte NE, operating since May 2025; America’s Heartland Packing, Wright City MO, a mixed fed-and-cow plant). Tyson Lexington (closed January 2026) and plants that buy mainly cull cows and bulls are excluded.
| Plants within 50 miles | Yards | Share of yards | One-time capacity (head) | Share of capacity |
|---|---|---|---|---|
| One (single-buyer geography) | 75 | 24.0% | 1,302,424 | 28.1% |
| Two or more (choice) | 88 | 28.2% | 1,867,558 | 40.3% |
| None (remote; freight penalty to any buyer) | 149 | 47.8% | 1,460,455 | 31.5% |
| Total, Kansas and Nebraska | 312 | 100% | 4,630,437 | 100% |
By state. In Kansas (196 yards, 3.35 million head) 48.5% of capacity has two or more plants within 50 miles, reflecting the Dodge City–Holcomb–Liberal cluster. In Nebraska (116 yards, 1.28 million head) only 19.1% of capacity does; 34.8% has a single nearby plant and 46.1% has none.
Who the single nearby buyer is. For the 75 single-plant yards the one plant within 50 miles is Tyson Holcomb (27 yards), Cargill Schuyler (19), JBS Grand Island (10), Sustainable Beef North Platte (9), National Beef Liberal (7) or Tyson Dakota City (3).
Limits. Fifty miles is a screening distance, not a market boundary: cattle are routinely hauled further, at a cost. The dataset covers Kansas and Nebraska only; Texas, Colorado and other feeding states are not yet represented from state sources. Capacity is one-time pen capacity as reported, not annual marketings.
4. The federal policy record
- RTI International, GIPSA Livestock and Meat Marketing Study (January 2007). Using packer transaction data from October 2002 to March 2005, the study found 61.7% of fed cattle bought in the cash or spot market and 28.8% through marketing agreements. It estimated that “a 10 percentage point increase in capacity utilization through AMAs is associated with a 0.4 cent per pound carcass weight decrease in the cash market price,” and concluded that cost savings and quality improvements from alternative marketing arrangements “outweigh the effect of potential oligopsony market power.”
- Concentration. USDA reports that the four largest packers handled 85% of steer and heifer slaughter in 2019 and 81% in 2020–2021, and a national fed-cattle packing HHI of 1,687 in 2021 (see Overview of the American Beef Industry).
- USDA AMS advance notice, “Price Discovery and Competition in Markets for Fed Cattle” (October 11, 2024). USDA wrote that in 2005 packers bought “roughly 55 percent of their cattle through cash negotiations” and that by 2021 spot transactions “accounted for 19%.”
- Packers and Stockyards Act rules. The “Inclusive Competition and Market Integrity” rule (published March 6, 2024, effective May 6, 2024) addresses discrimination, retaliation and deception in contracting. It did not change the “harm to competition” standard; a separate proposed rule, “Fair and Competitive Livestock and Poultry Markets” (June 2024), was withdrawn on January 16, 2025. USDA’s 2026 regulatory agenda lists the 2024 rule for rescission; as of July 2026 no formal proposal had been published.
- Cash-trade bills. Senator Grassley’s 2020 “50/14” bill would have required large packers to buy at least 50% of their slaughter on the spot market for delivery within 14 days. The Cattle Price Discovery and Transparency Act (S.4030 in the 117th Congress; reintroduced as S.228 in 2023) would instead set regional mandatory minimums for negotiated purchases and create a contract library. FAT found no record that either was enacted. Congress did direct USDA to create a Cattle Contracts Library pilot in the Consolidated Appropriations Act of 2022; AMS’s pilot page was last updated in April 2024.
5. Where the industry groups stand
- NCBA opposes a mandate: “One-size-fits-all solutions, such as the government mandate on cattle sales… is not the solution” (2022).
- R-CALF USA supports the 50/14 bill and urged Congress “to pass this important bill into law” (2021).
- U.S. Cattlemen’s Association supports the Cattle Price Discovery and Transparency Act (2023).
- Meat Institute opposes minimums, arguing they “could have the opposite effect, potentially imposing huge costs” (2021).
6. What the economics literature finds
- Schroeter, J.R. (1988), “Estimating the Degree of Market Power in the Beef Packing Industry,” Review of Economics and Statistics 70(1): 158–162.
- Schroeter, J.R. & Azzam, A.M. (1991), “Marketing Margins, Market Power, and Price Uncertainty,” American Journal of Agricultural Economics 73(4): 990–999.
- Azzam, A.M. & Schroeter, J.R. (1995), “The Tradeoff between Oligopsony Power and Cost Efficiency in Horizontal Consolidation,” AJAE 77(4): 825–836.
- Azzam, A.M. (1998), “Captive Supplies, Market Conduct, and the Open-Market Price,” AJAE 80(1): 76–83 (models how captive supplies can depress the spot price).
- Ward, C.E., Koontz, S.R. & Schroeder, T.C. (1998), “Impacts from Captive Supplies on Fed Cattle Transaction Prices,” Journal of Agricultural and Resource Economics 23(2): 494–514 (finds “small but often negative effects”).
- Xia, T. & Sexton, R.J. (2004), “The Competitive Implications of Top-of-the-Market and Related Contract-Pricing Clauses,” AJAE 86(1): 124–138.
- Crespi, J.M., Saitone, T.L. & Sexton, R.J. (2012), “Competition in U.S. Farm Product Markets: Do Long-Run Incentives Trump Short-Run Market Power?” Applied Economic Perspectives and Policy 34(4): 669–695.
- Saitone, T.L. & Sexton, R.J. (2017), “Concentration and Consolidation in the U.S. Food Supply Chain: The Latest Evidence and Implications for Consumers, Farmers, and Policymakers,” Federal Reserve Bank of Kansas City Economic Review.
- Brester, G.W., Swanser, K. & Crosby, J. (2022), “The Thinning Cash Cattle Market: Evaluating Sample Size, Policy Prescriptions, and Pricing Proxies,” Journal of Agricultural and Applied Economics 54(3).
The literature does not agree on how large the price effect of captive supply is; estimates vary by period, region and method, and some studies find efficiency gains that offset it. It does broadly support three points: alternative marketing arrangements now dominate fed-cattle procurement; a thin cash market is a weaker anchor for formula prices; and few plants per region compound both.
7. A definition: “captive in practice”
We propose that a feedlot be described as captive in practice if any of the following holds: (a) a packer owns it, or owns a controlling interest in its parent; (b) a documented agreement commits most of its finished cattle to one packer (the Five Rivers–JBS agreement is the clearest public example); or (c) it has one or no major fed-cattle plant within 50 miles, so that selling elsewhere carries a material freight and shrink cost. On FAT’s Kansas and Nebraska data, criterion (c) alone covers 72% of yards and 60% of capacity. Criterion (b) is almost certainly the largest group nationally, but it cannot be measured yard by yard from public data: LMR reports the aggregate contract share and never names the feedlot.
8. What this means for FAT’s 16 categories
Farm Animal Transparency (FAT) maps what a label discloses against the public record; it does not rate or recommend. Feedlot captivity sits in Category 16, Supply-Chain Intermediaries (every custodian between farm and processor), and connects to Category 7 (Processor) and Category 8 (Who). Full list of the 16 FAT categories: 1 USDA/FDA Required Basics; 2 Species; 3 Breed; 4 Country of Origin; 5 Farm; 6 Age at Slaughter; 7 Processor; 8 Who; 9 Brand; 10 Feed; 11 Animal Welfare; 12 Medicine; 13 Hormones; 14 Quality & Palatability; 15 Organic; 16 Supply-Chain Intermediaries. No federal rule requires a beef label to name the feedlot or to say whether the cattle were sold on contract.
9. The FAT App
The FAT App reads the establishment number on a beef package and, in about two seconds, at home or standing at the grocery meat case, shows the processing plant, its corporate parent and its FSIS enforcement history, and how many of the 16 categories the label discloses. It is free, has no paywall, and no emails are collected.
10. Recommendations
- Congress: reauthorize Livestock Mandatory Reporting for multiple years rather than by continuing resolution.
- USDA AMS: resume publication of the annual LMR purchase-type breakdown by region (the located series ends in 2021) and of Packers and Stockyards concentration tables.
- Feedlots and producers: when describing a yard as independent, say which of the three ties has been checked.
- FAT: add Texas and Colorado feedlots to the dataset from state sources.
Sources
- USDA AMS – Annual LMR Live Cattle Purchase Type Breakdown by Region, 2005–2021
- USDA AMS – AMS_2474, 5 Area Weekly Direct Slaughter Cattle – Formulated, Forward Contract and Negotiated Grid Purchases (week ending Sept. 20, 2026)
- USDA AMS – AMS_2477, 5 Area Weekly Weighted Average Direct Slaughter Cattle, negotiated cash (week ending Sept. 20, 2026)
- Federal Register – USDA AMS information-collection notice on LMR authority (Aug. 26, 2026)
- Congressional Research Service (Greene) – “Livestock Mandatory Reporting Act: Overview for Reauthorization in the 116th Congress,” R45777 (June 19, 2019)
- Federal Register – USDA AMS, “Price Discovery and Competition in Markets for Fed Cattle,” ANPR (Oct. 11, 2024)
- American Farm Bureau Federation – “Examining Cattle Transactions in the U.S.” (May 29, 2020)
- RTI International – GIPSA Livestock and Meat Marketing Study, Vol. 1 (January 2007)
- GIPSA Livestock and Meat Marketing Study, final report (copy hosted by LMIC)
- USDA AMS – Packers and Stockyards Division Annual Report 2020
- USDA AMS – Packers and Stockyards Division Annual Report 2021 & 2022
- USDA AMS – Inclusive Competition and Market Integrity Under the Packers and Stockyards Act (2024 final rule)
- SBA Office of Advocacy – AMS withdraws “Fair and Competitive Livestock and Poultry Markets” proposed rule (Jan. 21, 2025)
- Texas Farm Bureau – “USDA to rescind meat sector competition rules” (July 17, 2026)
- Sen. Grassley – 50/14 cattle pricing bill text (May 12, 2020)
- S.4030 (117th Congress) – Cattle Price Discovery and Transparency Act, reported text
- S.228 (118th Congress) – bill summary
- USDA AMS – Cattle Contracts Library Pilot Program
- Progressive Cattle – “JBS sells Five Rivers Cattle Feeding for $200 million” (trade press, Jan. 2018)
- Five Rivers Cattle Feeding – Locations
- Investigate Midwest – “As feedlots become larger, the Big Four expand their market share” (April 1, 2026)
- Oklahoma State University Extension – “Managing Shrink and Weighing Conditions in Beef Cattle,” AFS-3257 (2017)
- Tyson Foods – Beef network restructuring (Aug. 13, 2026)
- JBS Foods USA – U.S. Cattle Buyers (plant locations)
- Cargill – Beef facility contact list
- National Beef – Our Businesses
- Sustainable Beef (North Platte) – overview, production began May 2025 (Wikipedia)
- High Plains Journal – America’s Heartland Packing opens in Missouri (May 2025)
- Morning Ag Clips – NCBA opposition to government mandate (Apr. 27, 2022)
- R-CALF USA – Support for the 50/14 bill (Mar. 24, 2021)
- USCA – Cattle Price Discovery and Transparency Act reintroduced (Feb. 2, 2023)
- Meat Institute – On mandatory negotiated-trade minimums (Oct. 5, 2021)
- RePEc – Azzam publications (Schroeter & Azzam 1991; Azzam & Schroeter 1995; Azzam 1998)
- Schroeter (1988), Review of Economics and Statistics (RePEc record)
- Ward, Koontz & Schroeder (1998), Journal of Agricultural and Resource Economics
- Xia & Sexton (2004), American Journal of Agricultural Economics
- Crespi, Saitone & Sexton (2012), Applied Economic Perspectives and Policy
- Saitone & Sexton (2017), Kansas City Fed Economic Review (UC Davis publication list)
- Brester, Swanser & Crosby (2022), Journal of Agricultural and Applied Economics
- Farm Animal Transparency – Understanding the 16 FAT Categories
Companion FAT maps (rebuilt September 24, 2026 on the verified plant list and EPA ECHO data): Captivity Tiers Map · Feedlot Supply Map · Captive Feedlot Map · Feedlot Enforcement Map · Captive Feedlot Enforcement Map · Integrated Map
Working paper. First prepared April 30, 2026; revised September 24, 2026. Feedlot statistics are FAT’s own calculations from the datasets named in Section 3. Corrections welcome: dirkadams@farmanimaltransparency.com.