SEAFOOD RESEARCH SERIES | RESEARCH PAPER
Overview of the American Farm-Raised Catfish Industry
Structure, ownership, trade and regulation of U.S. catfish farming and processing, updated for USDA’s 2026 production reports, the August 2026 antidumping review of Vietnamese fish fillets and the July 2026 Section 301 tariffs.
Prepared for publication by Farm Animal Transparency | September 2026
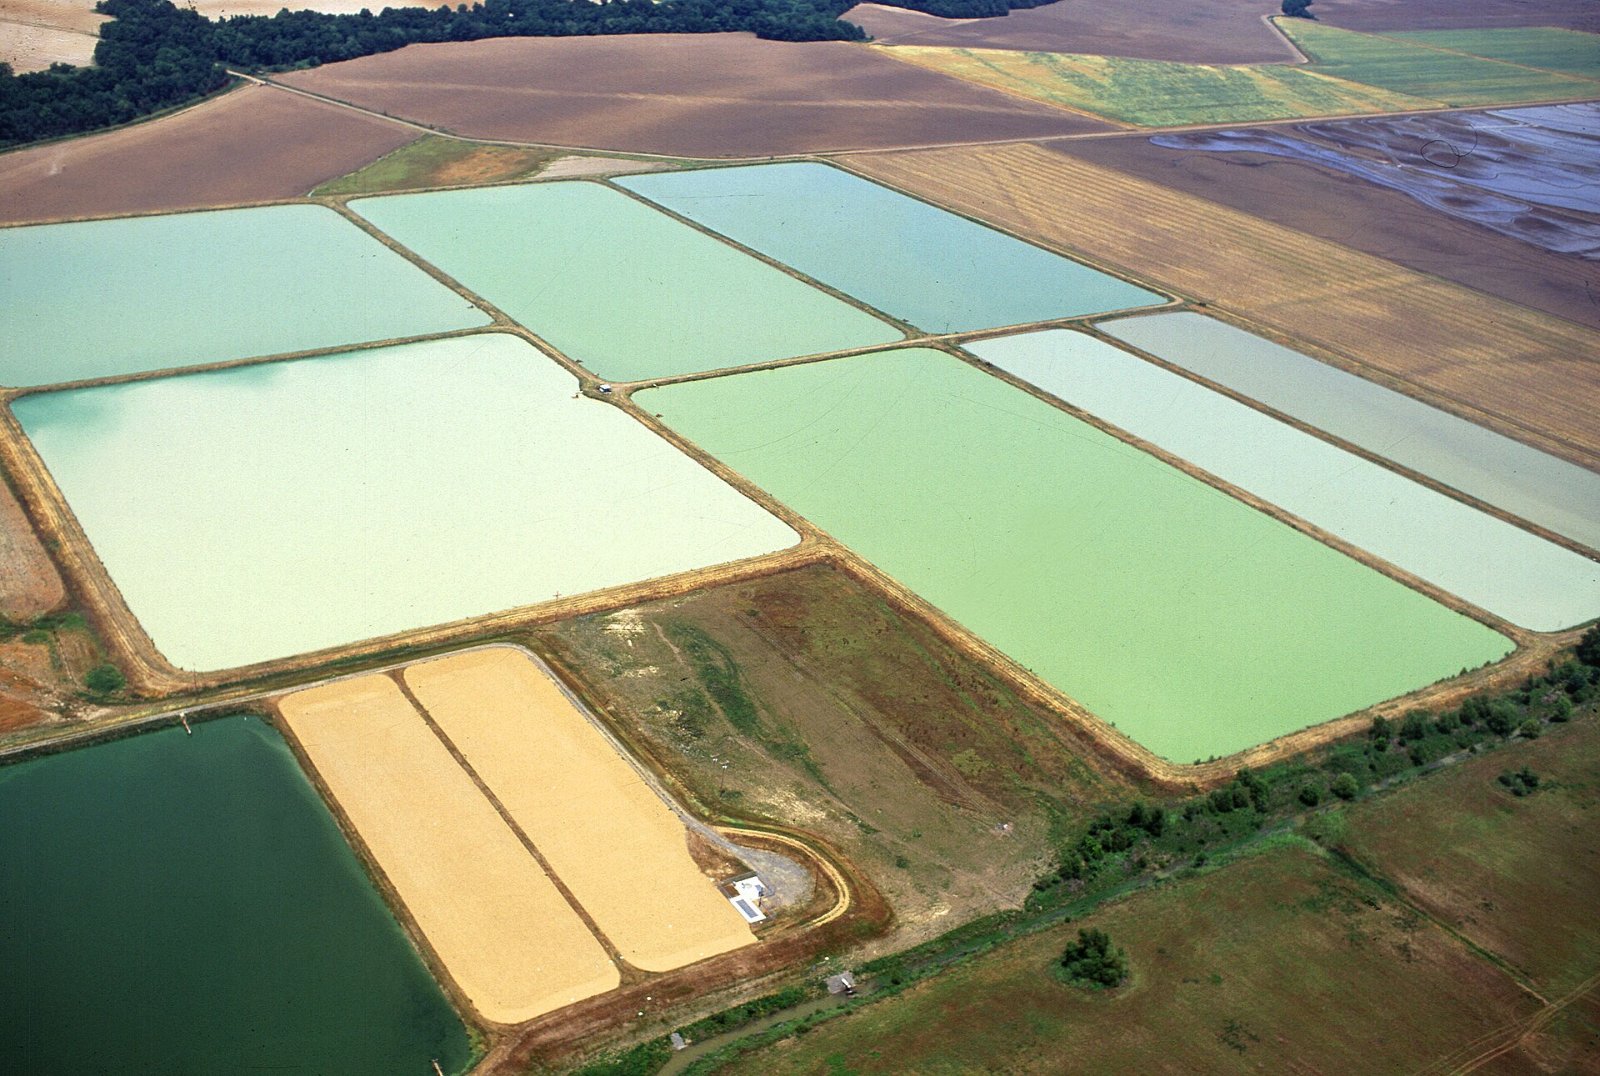
U.S. catfish is raised on about 48,000 acres, mostly in Mississippi and Alabama, and sold to a handful of plants. Imported pangasius from Vietnam competes with it on price.
| At a glance |
| A small, concentrated farm sector. Growers sold $393.8 million of catfish in 2025 from 48,115 water acres (January 1, 2026). Mississippi accounted for 59% of sales and Alabama 25%. Processors bought 92.7% of foodsize fish. |
| Less than half its former size. Processors bought 662 million pounds of catfish in 2003. Growers sold 330 million pounds of foodsize fish in 2025. |
| Imports are large. The United States imported 244.3 million pounds of frozen pangasius fillets from Vietnam in 2025, valued at $327.9 million (NOAA trade data). |
| Trade remedies stay in place. The 2003 antidumping order on Vietnamese frozen fish fillets was continued on June 24, 2026 after a fourth sunset review. Commerce’s August 2026 review set rates of $0.38–$1.00 per kilogram for reviewed exporters and kept a $2.39 per kilogram Vietnam-wide rate. A 12.5% Section 301 tariff on Vietnamese goods began July 24, 2026. |
| USDA, not FDA, inspects catfish. Since 2016 all fish of the order Siluriformes, including imported basa and swai, have been inspected by USDA’s Food Safety and Inspection Service (FSIS). No federal law governs how farmed fish are raised or killed. |
Abstract
This paper describes the U.S. farm-raised catfish industry as of September 2026: its size and location, the processors that buy the fish and who owns them, how the fish are produced, the import competition from Vietnamese pangasius and the trade measures around it, and the federal rules on inspection, labeling, environment and welfare. Farm and plant economics (costs, margins, prices and yields) are covered in the companion paper, The Siluriformes Business. FSIS inspection is covered in detail in The Catfish Exception and How USDA Polices Siluriformes Processing.
1. Summary
U.S. catfish farming, which the American Farm Bureau Federation calls America’s top farm-raised fish, is small next to meat and poultry and has contracted for two decades. Production is concentrated in Mississippi, Alabama and Arkansas, and almost all foodsize fish are sold to a small number of processors, several of which also farm. Imported pangasius, sold as basa or swai, arrives in large volume: 244 million pounds of frozen fillets in 2025, against 330 million pounds of live catfish sold by U.S. growers. Antidumping duties, tariffs, a federal naming law and USDA inspection all shape how imports compete with domestic catfish. Farmed fish fall outside federal humane-slaughter law, and there is no federal standard for how they are raised.
2. Industry overview
2.1 Scale
USDA’s National Agricultural Statistics Service (NASS) reported total catfish sales of $393.8 million in 2025, up 1% from $389.5 million in 2024. Foodsize fish accounted for $366.9 million: 219.9 million fish weighing 330.0 million pounds, sold at an average of $1.11 a pound. The main species is channel catfish (Ictalurus punctatus). A 2019–2020 survey found that about 53% of water area in Alabama, Arkansas and Mississippi was used for hybrid catfish (Hegde et al., 2022).
2.2 Where catfish are raised
| State | Water acres, Jan. 1, 2026 | Total sales, 2025 | Share of U.S. sales | Foodsize pounds sold, 2025 |
|---|---|---|---|---|
| Mississippi | 28,500 | $233.3 million | 59% | 194.3 million |
| Alabama | 10,300 | $99.5 million | 25% | 97.5 million |
| Arkansas | 3,200 | $25.1 million | 6% | 15.9 million |
| Other states | 4,515 | $16.6 million (some states withheld) | — | 22.3 million |
| United States | 48,115 | $393.8 million | 100% | 330.0 million |
Source: USDA NASS, Catfish Production (Feb. 9, 2026). Shares are FAT’s calculation. NASS publishes Texas, California and North Carolina separately in some tables and notes that “the top four States (Mississippi, Alabama, Arkansas, and Texas) accounted for 96 percent of the United States total sales.”
Water acres fell 8% in a year, from 52,070 on January 1, 2025. Alabama lost the most (12,100 to 10,300). By July 1, 2026 the three reporting states had 41,100 acres: Mississippi 27,900, Alabama 9,700 and Arkansas 3,500. The Catfish Institute says that 94% of U.S. farm-raised catfish is raised in Alabama, Arkansas, Louisiana and Mississippi.
The July 2026 report points to smaller supplies ahead. On July 1 the three states held 93.4 million foodsize fish, about the same as a year earlier, but stockers were down 16% to 153 million and fingerlings and fry down 7% to 227 million. Growers intended to use 32,100 acres for foodsize fish in the second half of 2026, down 6%, while fingerling acres rose 24% to 6,165 and 805 acres were scheduled for renovation.
2.3 The long decline
- Processing volume. Processors bought 662 million pounds of catfish in 2003, the peak year, and 630 million pounds in 2004 (NASS Catfish Processing). In 2025 growers sold 330 million pounds of foodsize fish, 92.7% of it to processors.
- Acreage. Catfish ponds covered about 200,000 acres at the peak in the early 2000s and fewer than 50,000 today, according to a June 2026 American Farm Bureau Federation analysis (secondary).
- Farms. The same analysis reported 389 catfish farms in 2023, down from more than 1,300 in 1998 (secondary).
- Inventory. The foodsize fish inventory fell from 158.7 million on January 1, 2025 to 112.9 million a year later (NASS).
Rising feed and other costs, farm prices near or below cost, and competition from lower-priced imports are the causes most often cited. The cost side is examined in The Siluriformes Business.
3. Market structure and ownership
3.1 Processors
The Catfish Institute (TCI), the industry’s marketing organization, lists eleven certified processors of U.S. farm-raised catfish. The table combines that list with what the companies say about their own history and ownership.
| Processor (TCI list) | Location | Ownership and history (company sources unless noted) |
|---|---|---|
| Delta Pride and Country Select (Consolidated Catfish Producers, LLC) | Isola, MS | Traces to ConAgra’s Country Skillet brand (1967) and a 1991 joint venture with Fishco, a corporation of 120 farmer-stockholders. Dick Stevens and three local farmers bought ConAgra’s stake in 1997; the company became Consolidated Catfish Producers in 2002. It combined sales, marketing and distribution with Delta Pride Catfish in 2006 and fully consolidated by 2008. In 2019 it leased the South Fresh Farms facility in Alabama. |
| Heartland Catfish Company | Itta Bena, MS | Founded 1996 by the Tackett and Walker families; family-controlled. Bought the Southern Pride plant in Greensboro, Alabama in 2008 and consolidated back to Itta Bena in 2020. Reports capacity rising to 115 million pounds a year by 2010. Supplied by Tackett Fish Farms, which had about 9,300 water acres at its peak. |
| America’s Catch | Itta Bena, MS | Describes itself as the largest distributor of farm-raised catfish in the United States, operating from hatchery to delivery. |
| Simmons Catfish | Yazoo City, MS | Family-owned. Harry Simmons began farming in 1977 and opened the processing plant in 1982; the third generation now works in the business. |
| Harvest Select | Uniontown, AL | Founded 1991 by five west Alabama farmers; farms, harvests, processes and distributes; more than 250 employees. First U.S. catfish processor certified under Best Aquaculture Practices (2008). |
| Freshwater Farms Products, LLC | Belzoni, MS | Not reviewed |
| Pride of the Pond | Tunica, MS | Not reviewed |
| Superior Catfish | Macon, MS | Not reviewed |
| Guidry’s | Breaux Bridge, LA | Not reviewed |
| Haring Catfish | Wisner, LA | Not reviewed |
All of the processors on the TCI list are U.S.-based. The five whose histories FAT reviewed describe themselves as privately or family-held, and none reported foreign ownership. The list covers TCI-certified plants only; other FSIS-inspected Siluriformes establishments, including importers’ and repackers’ facilities, appear on FAT’s catfish map.
Company histories show how the processing side grew as farm output shrank. Heartland reports processing capacity of 12 million pounds a year when it opened in 1996, 75 million by 2001 and 110 million by 2008, when it added the Alabama plant. Consolidated Catfish Producers says its Isola plant “has experienced six major expansions and has one of the highest live fish processing capacities in the industry.” A 2006 trade report on the Delta Pride–Country Select combination said the combined sales would “exceed $150 million” and quoted the companies’ leaders that “consolidations and mergers are long overdue for the catfish industry” (secondary: Progressive Grocer).
3.2 Concentration
No federal agency publishes processor market shares or concentration ratios for catfish, and FAT could not find a current, sourced estimate. What the public record does show is structural: NASS reports that 92.7% of foodsize fish went to processors in 2025, TCI lists eleven certified processors, and seven of them are in Mississippi. Live catfish are hauled in aerated tanks, so a grower sells to plants within trucking distance of the ponds.
Market definition matters. If imported pangasius is treated as a substitute for domestic catfish, U.S. processors face a large import competitor. If the market is U.S. farm-raised catfish alone, it is served by a few firms.
3.3 Vertical integration
Several processors also farm. Heartland, Simmons, Harvest Select and America’s Catch each describe control of farming as well as processing. Other plants buy from independent growers. FAT found no public data on how much catfish is raised on processor-owned ponds or under contract.
4. How catfish are produced
Figures in this section are from Mississippi State University (MSU) Extension unless noted.
Broodfish and spawning. Channel catfish spawn in spring when water temperature rises above 70°F and holds around 75°F. Farmers place spawning containers in brood ponds and check them every two or three days for egg masses. Reliable spawners are at least three years old and three pounds. Hybrid catfish are produced by injecting female channel catfish with a hormone to induce ovulation, stripping the eggs and fertilizing them with sperm from blue catfish males, because the two species do not mate naturally. USDA’s Agricultural Research Service reported that hybrids show “better growth, higher survival, and better meat yield” and that farmers can raise production 20 to 30 percent by using them. ARS reported that hybrid fry production rose from 30 million in 2007 to about 150 million by 2011, when hybrids were about 20 percent of catfish harvested; by 2019–2020 hybrids occupied about 53% of tristate water area (Hegde et al.).
Hatchery and fingerlings. Eggs hatch in five to eight days; fry stay in the hatchery four to ten days before stocking in nursery ponds. Over five to ten months they grow to fingerlings of 3 to 8 inches, fed a floating pellet of 32–35% crude protein. Survival above 60% from fry to fingerling is considered very good. In 2020, 83% of fingerling farms vaccinated against enteric septicemia of catfish with an oral vaccine (Hegde et al.).
Grow-out. New ponds average 8 to 12 acres with 5.5 to 6 feet of water. Stocking rates range “from less than 3,000 fish/acre to more than 18,000 fish/acre.” Intensive ponds use 5 to 10 horsepower of aeration per acre and produce 12,000 to 18,000 pounds per acre; split ponds produce 15,000 to 20,000 pounds per acre. The tristate survey counted 6,315 hectares of intensively aerated ponds and 1,176 hectares of split ponds, an average aeration rate of 7.8 kW per hectare, and automated oxygen monitors on 97% of farms (Hegde et al.). The full cycle from egg to a 1- to 2-pound food fish takes 18 to 36 months.
Harvest. Fish are taken off feed two to three days before harvest and checked for off-flavor, and processors schedule only ponds that are “on-flavor.” Crews seine the pond, weigh fish in a lift net and load them into oxygenated tanks for hauling to the plant. Seining takes a crew of at least five people. MSU reports that a newer seine design with braided polyethylene mesh and a zipper system caught about 20% more fish and cut seining time by 45%. Fish bound for processing are hauled at higher densities than fish for other markets because they are held only briefly before slaughter.
Processing. At the plant, fish are “exposed to a low voltage electric current to stun the fish,” then processed in less than 30 minutes into whole dressed fish, steaks, fillets, nuggets and strips, and chilled below 41°F. CFA and TCI say certified plants have “combined processing capability of more than 10 million pounds of U.S. Farm-Raised Catfish per week.”
5. Trade and imports
5.1 The import market
Imported “catfish” is mostly pangasius, farmed in Vietnam and sold as basa or swai. MSU, using NOAA Fisheries data, reported that U.S. catfish imports averaged 243.3 million pounds and $378.5 million a year from 2019 to 2024, with Vietnam supplying 89.5% of the value and China 8.4%. Over the same period the average import price fell from $2.06 to $1.32 a pound.
| Frozen pangasius fillets from Vietnam (HTS 0304.62.0020) | Pounds (product weight) | Customs value |
|---|---|---|
| 2025, full year | 244.3 million | $327.9 million |
| January–July 2025 | 147.3 million | $194.6 million |
| January–July 2026 | 130.6 million | $177.3 million (−9%) |
Source: FAT totals of NOAA Fisheries foreign trade records (FOSS), queried September 24, 2026. In 2025 the fillets entered through ports from Los Angeles and Houston to New York and Norfolk.
Import pounds are fillet weight; domestic sales are live weight, and a fillet is only part of the fish. The two cannot be added into a single market share without a conversion factor, which FAT has not applied. Even without a conversion, imports of frozen pangasius fillets alone approach the live weight of all foodsize catfish sold by U.S. growers.
5.2 Antidumping duties
The Department of Commerce issued an antidumping order on certain frozen fish fillets from Vietnam on August 12, 2003. The order is reviewed each year for the period August 1 to July 31. Recent actions:
Rates are set in dollars per kilogram for each exporter that requests and qualifies for a separate rate. Exporters that do not qualify are treated as part of a single “Vietnam-wide entity,” whose rate of $2.39 per kilogram is far above the rates of the reviewed companies. Importers pay cash deposits at the current rate on entry, and the final duty is set when a review for that period is completed.
- Vinh Hoan removed (January 2025). After the United States and Vietnam signed an agreement settling WTO dispute DS536, Commerce revoked the order for Vinh Hoan Corporation and its affiliated companies, effective for entries on or after August 1, 2021 (90 FR 8120).
- 2022–2023 review (June 2025). Seven exporters, including Bien Dong, Can Tho Import-Export, Nam Viet and NTSF, received rates of $0.00 per kilogram. The Vietnam-wide rate remained $2.39 per kilogram.
- Fourth sunset review (2026). Commerce found in April 2026 that revoking the order would likely lead to dumping at margins up to 63.88%. The U.S. International Trade Commission voted on June 24, 2026 that revocation would likely lead to material injury, and the order was continued (91 FR 39070).
- 2023–2024 review (August 2026). Final rates: Bien Dong Seafood $1.00, Can Tho Import Export Seafood $0.84, Nam Viet $0.84 and NTSF Seafoods $0.38 per kilogram. Reviews of 25 companies were rescinded, and the Vietnam-wide entity rate stayed at $2.39 per kilogram (91 FR 52286).
- Court remand (September 2026). Following a Court of International Trade judgment in Catfish Farmers of America v. United States (No. 24-00082), Commerce raised the 2021–2022 rate for five exporters from $0.18 to $0.20 per kilogram.
5.3 Tariffs
On February 20, 2026 the U.S. Supreme Court held that the reciprocal tariffs imposed under the International Emergency Economic Powers Act were not authorized (secondary: Vietnam Briefing). The administration then applied a temporary surcharge under Section 122 of the Trade Act of 1974 (same source). Since July 24, 2026, products of Vietnam have been subject to a 12.5% tariff under Section 301, following USTR’s forced-labor investigations of 60 economies (91 FR 47318). FAT has not confirmed whether frozen fish fillets fall within any product exclusion in the notice’s annexes. The tariff is in addition to any antidumping duty.
5.4 Names and origin labels
The name “catfish.” Since the 2002 Farm Bill (Pub. L. 107–171, sec. 10806), a food is misbranded “if it purports to be or is represented as catfish, unless it is fish classified within the family Ictaluridae” (21 U.S.C. 343(t)). Pangasius, in the family Pangasiidae, must be sold under other names such as basa, swai or pangasius.
Country of origin. USDA’s country-of-origin labeling rules for fish (7 CFR Part 60) require retailers to state the country of origin of farm-raised and wild fish, including fillets and nuggets, and whether the fish is “wild and/or farm-raised.” Two exemptions matter for catfish: “food service establishments” such as restaurants are exempt, and fish used as an ingredient in a processed food item is excluded. A diner therefore has no federal right to know whether the catfish on the plate is domestic or imported, or whether it is catfish at all.
6. Regulation
6.1 USDA inspection of Siluriformes
The 2008 Farm Bill made catfish subject to the Federal Meat Inspection Act (FMIA), and section 12106 of the 2014 Farm Bill extended coverage to “all fish of the order Siluriformes,” which includes pangasius. FSIS published its final rule on December 2, 2015 (80 FR 75590). FSIS took over domestic inspection on March 1, 2016 and import inspection on April 15, 2016; full enforcement followed an 18-month transition ending September 1, 2017.
Catfish inspection is not identical to meat inspection. The final rule states that the FMIA’s sections on ante-mortem and post-mortem inspection and humane slaughter (21 U.S.C. 603 and 604) “do not apply to catfish.” Since September 1, 2017, FSIS has covered plants that slaughter Siluriformes “once per production shift” rather than during all hours of operation (82 FR 41501). Foreign countries may export only if FSIS finds their system equivalent; FSIS made that finding for China, Thailand and Vietnam in November 2019. FSIS lists countries whose shipments certified after March 1, 2018 are no longer eligible, including Bangladesh, Canada, Mexico, Myanmar, Nigeria and Pakistan. In the final rule FSIS estimated the annualized cost to the domestic industry at about $326,550, or about $0.0008 per pound of processed fish.
6.2 The transfer debate
The move from FDA to USDA was contested. In 2012 the Government Accountability Office (GAO) concluded that responsibility for inspecting catfish “should not be assigned to USDA,” found that FSIS had used “outdated and limited information in its risk assessment,” and recommended that Congress consider repealing the Farm Bill provisions. In December 2016 GAO testified that it had estimated the program would duplicate other federal seafood inspection at about $14 million a year, and that FSIS later lowered its cost estimate to $2.6 million after an FDA–USDA memorandum of understanding. On May 25, 2016 the Senate passed S.J.Res. 28 to disapprove the FSIS rule; it did not become law, and the program remains in force. The history is covered in The Catfish Exception.
6.3 Environmental permits
Under the Clean Water Act, a warm-water fish farm is a concentrated aquatic animal production facility, and needs a discharge permit, only if it discharges at least 30 days a year and produces at least 100,000 pounds a year. EPA’s definition excludes “closed ponds which discharge only during periods of excess runoff” (40 CFR 122, appendix C). EPA’s effluent guidelines for aquatic animal production (40 CFR 451) apply to flow-through, recirculating, net-pen and submerged-cage systems, not to ponds. Catfish ponds are therefore outside the federal effluent guidelines, and ponds that discharge only after heavy rain do not meet the federal permit definition. The processing plants, which discharge wastewater, are regulated separately; their permit and compliance records appear on FAT’s catfish map.
6.4 Birds and wildlife law
Fish-eating birds are protected under the Migratory Bird Treaty Act. Since 2021, USFWS has issued a special double-crested cormorant permit to state and tribal wildlife agencies (50 CFR 21.123), covering depredation at state- and tribal-run aquaculture facilities among other uses. Private farms seeking lethal control apply for an individual depredation permit (50 CFR 21.100); no permit is needed simply to scare or herd birds. The American Farm Bureau Federation estimated direct bird-predation losses at about $65 million a year, including about $47 million in fish eaten by cormorants (secondary).
7. Fish health
Disease is a major production risk. The Farm Bureau analysis summarized research estimating industry disease costs at $15.5 to $45.9 million a year, with edwardsiellosis about 31% of reported cases, and a seven-year Alabama survey that found average disease losses of $668 per acre per year (secondary). The main tools are water-quality management, oral vaccination of fingerlings against enteric septicemia, and hybrid fish.
8. Animal welfare
No federal rearing or slaughter standard. The Humane Methods of Slaughter Act applies to “cattle, calves, horses, mules, sheep, swine, and other livestock” (7 U.S.C. 1902). FSIS’s catfish rule states that the FMIA’s humane-slaughter section does not apply to catfish. FAT found no federal regulation that sets stocking density, water quality, handling or transport standards for farmed fish. In 2025 U.S. growers sold 219.9 million foodsize catfish (NASS).
What plants do. MSU Extension describes catfish being stunned with a low-voltage electric current at the plant. FAT has not found public data on how consistently stunning is applied across plants or how effective it is.
Rearing conditions. Stocking rates range widely, from under 3,000 to over 18,000 fish per acre. Farms rely on aerators and automated oxygen monitors to keep fish alive in crowded, heavily fed ponds. These practices protect survival and growth; they are production measures, not welfare standards.
Other jurisdictions. The European Union’s slaughter regulation (Council Regulation 1099/2009) requires that animals “be spared any avoidable pain, distress or suffering during their killing,” but for fish, “only the requirements laid down in Article 3(1) shall apply”; the detailed stunning rules for land animals do not. The regulation’s recitals give the reason: fish differ physiologically from land animals, and research on fish stunning was less developed.
Voluntary certification. Harvest Select became the first U.S. catfish processor certified under Best Aquaculture Practices (BAP) in 2008, and America’s Catch displays a BAP mark. FAT has not verified how many catfish farms hold third-party certification.
9. Industry organizations
Catfish Farmers of America (CFA) is the producers’ trade association. It was the lead plaintiff in the Court of International Trade case on the 2021–2022 antidumping review noted above. The Catfish Institute (TCI) was “formed in 1986 by a group of catfish farmers and feed manufacturers” to promote U.S. farm-raised catfish, and maintains the certified-processor list.
10. What this means for FAT’s framework
Farm Animal Transparency (FAT) maps what a label discloses against the public record; it does not rate or recommend. For catfish the record points to five issues:
- Concentration without data. Processing appears concentrated, but no public source measures it. FAT should report the number of inspected processors and the share of fish sold to processors rather than an estimated four-firm ratio.
- Integration. Several processors also farm. FAT should record integration company by company from company statements and FSIS records.
- Imports. Imported pangasius fillets approach domestic output in volume. FAT should report domestic and imported supply separately and show the origin label (Cat. 4 Country of Origin) and species name (Cat. 2 Species) as key disclosures.
- Regulation split across agencies. FSIS inspects plants; EPA and states regulate discharges; USFWS regulates birds; Commerce and USTR set duties and tariffs. No agency sets farm-level standards. FAT should note which of these records are public for each plant.
- Welfare. Farmed fish are outside federal humane-slaughter law. Where a label or company makes a welfare or stunning claim, FAT should treat it as unverified unless a third-party standard or public record supports it (Cat. 11 Animal Welfare).
For a shopper, a retail package must show country of origin and “farm-raised,” and only Ictalurid fish may be called catfish. In a restaurant, none of that is required.
11. The FAT App
Catfish products from U.S. FSIS-inspected plants carry an establishment number on the package. The FAT App reads that number and shows which plant handled the product, its corporate parent and its FSIS enforcement history, alongside how many of the 16 FAT categories the package discloses. It is free, has no paywall, and no emails are collected.
12. Recommendations
- USDA NASS: resume a regular catfish processing series. The monthly Catfish Processing report, which tracked pounds processed and prices paid to growers, has no release in USDA’s archive after February 2014.
- USDA and Commerce: publish processor-level or regional concentration measures for catfish, as USDA does for fed cattle, so that buyer power can be measured rather than estimated.
- FSIS: make it easy to see, by establishment number, whether a Siluriformes plant slaughters domestic fish or repacks imported product.
- Researchers and reporters: state whether import figures are fillet weight or live weight before comparing them with domestic production.
Related FAT maps
FAT’s catfish supply-chain map shows FSIS-inspected Siluriformes plants alongside EPA ECHO permit compliance records, so readers can see where catfish is processed and review each facility’s public record.
Sources
- USDA NASS – Catfish Production (Feb. 9, 2026)
- USDA NASS – Catfish Production (July 15, 2026)
- USDA NASS – Catfish Processing (Feb. 22, 2005; 2003 and 2004 annual totals)
- American Farm Bureau Federation, Market Intel – “America’s Top Farm-Raised Fish Faces Growing Pressures” (June 11, 2026; secondary summary of university research)
- Hegde et al. – “Technological progress in the US catfish industry,” Journal of the World Aquaculture Society 53(2) (2022; abstract record)
- The Catfish Institute – U.S. Farm-Raised Catfish Certified Processors
- The Catfish Institute – Frequently Asked Questions
- Catfish Farmers of America / TCI – Farming and Processing
- Delta Pride Catfish – About (company history)
- Progressive Grocer – “Catfish Suppliers Merge” (trade press, 2006)
- Heartland Catfish Company – Company history
- America’s Catch – Company website
- Simmons Catfish – About Us
- Harvest Select – Our Story
- Mississippi State University Extension – Production Phases and Systems
- Mississippi State University Extension – Production Process for Channel Catfish
- Mississippi State University Extension – Harvesting, Loading, and Transport
- Mississippi State University Extension – Processing
- USDA ARS, Agricultural Research – “Producing Better Catfish the Hybrid Way” (Nov./Dec. 2013)
- Mississippi State University Extension – Posadas, “Direct Revenues From Tariffs and Their Impacts on Prices of U.S. Catfish Imports,” Mississippi MarketMaker Vol. 15, No. 6 (June 17, 2025)
- NOAA Fisheries – Foreign Fishery Trade Data (FOSS), imports of frozen pangasius fillets, HTS 0304.62.0020 (queried Sept. 24, 2026)
- Federal Register – Commerce, Frozen Fish Fillets From Vietnam: Notice of Partial Revocation (90 FR 8120, Jan. 24, 2025)
- Federal Register – Commerce, Frozen Fish Fillets From Vietnam: Final Results of Administrative Review, 2022–2023 (June 18, 2025)
- Federal Register – Commerce, Final Results of the Expedited Fourth Sunset Review (91 FR 20099, Apr. 15, 2026)
- Federal Register – Commerce, Continuation of Antidumping Duty Order (91 FR 39070, June 29, 2026)
- Federal Register – Commerce, Final Results of Administrative Review, 2023–2024 (91 FR 52286, Aug. 13, 2026)
- Federal Register – Commerce, Notice of Court Decision Not in Harmony and Amended Final Results, 2021–2022 (Sept. 22, 2026; via Justia)
- Vietnam Briefing – “US Supreme Court Blocks Trump’s Tariffs: Impacts on Vietnam-US Trade” (Feb. 27, 2026; secondary)
- Federal Register – USTR, Notice of Actions in Section 301 Forced-Labor Investigations (91 FR 47318, July 28, 2026)
- USTR – “USTR Takes Action in Forced Labor Section 301 Investigations” (July 23, 2026)
- U.S. Code – 21 U.S.C. 343(t), “catfish” labeling (govinfo)
- eCFR – 7 CFR Part 60, Country of Origin Labeling for Fish and Shellfish
- Federal Register – FSIS, Mandatory Inspection of Fish of the Order Siluriformes, final rule (80 FR 75590, Dec. 2, 2015)
- FDA – “FDA Transfers Siluriformes Fish Inspection to USDA” (May 2, 2016)
- Federal Register – FSIS, Changes to Inspection Coverage in Establishments That Slaughter Siluriformes (82 FR 41501, Sept. 1, 2017)
- USDA FSIS – Constituent Update: equivalence determinations for China, Thailand and Vietnam (Nov. 1, 2019)
- USDA FSIS – Inspection of Siluriformes
- GAO – Seafood Safety: Responsibility for Inspecting Catfish Should Not Be Assigned to USDA (GAO-12-411, May 2012)
- GAO – Seafood Safety: Status of Issues Related to Catfish Inspection (GAO-17-289T, Dec. 7, 2016)
- Congress.gov – S.J.Res. 28, 114th Congress (passed Senate May 25, 2016)
- eCFR – 40 CFR Part 122, Appendix C: Criteria for Concentrated Aquatic Animal Production Facilities
- eCFR – 40 CFR Part 451, Concentrated Aquatic Animal Production Point Source Category
- eCFR – 50 CFR 21.123, Special double-crested cormorant permit
- eCFR – 50 CFR 21.100, Depredation permits
- U.S. Code – 7 U.S.C. 1902, Humane methods of slaughter (govinfo)
- EUR-Lex – Council Regulation (EC) No 1099/2009 on the protection of animals at the time of killing
- Farm Animal Transparency – Understanding the 16 FAT Categories
Working paper. First prepared March 28, 2026; revised September 24, 2026 with data as of that date. Corrections welcome: dirkadams@farmanimaltransparency.com.